Nooga Strong - FFL
Services Page
Home > Services Page Overview
tell us your plan, we find the product to match your needs
You Call Us. We Shop for the best rates.
or you dont pay
You have insurance needs and goals.
We simply listen to your plan and get you the best coverage at the best rate.
A-Rated Carriers
Free 30-Minute Review
No Obligation, Ever






need life & health insurance?
Not Sure Which One I Need? That's the Normal Place to Start.
Most people arrive knowing the problem, not the product name.
Pick the problem — we'll name the product.
Which One Sounds Best For You?
TERM LIFE
I need the most coverage for the least money, for a set number of years.
WHOLE LIFE
I want permanent coverage that builds cash value I can actually use.
IUL
I want index-linked growth with a contractual floor under it.
FINAL EXPENSES
I want my funeral paid for without my family fundraising.
ANNUITIES
I want a paycheck in retirement that doesn't stop while I'm alive.
HEALTH INSURANCE
I need coverage between jobs, or off the exchange. Or during Medicare, Medicaid enrollments
MORTGAGE PROTECTION
I need the house paid off if I'm gone, plus a year or two of income.
INCOME PROTECTION
I need my paycheck replaced if I can't work.
NEED SOMETHING?
Let me know what else you need and we can figure it out together
Prompt: Generate Image for this exact pain point SOLUTION, realistic
01 — TERM LIFE
The most coverage for the least money, for a set number of years
Term life covers you for 10, 20 or 30 years and then ends. Because it expires, it costs a fraction of permanent coverage — which is why it's the right tool for temporary obligations like a mortgage or the years your children still depend on you. Two of our most popular products are term policies shaped around a specific bill.
Level Term
A fixed premium and a fixed death benefit for 10, 20 or 30 years. The simplest policy there is, and usually the cheapest per dollar of coverage.
Income Protection
Term structured to replace your paycheck, with the CBO100 cash-back option — pay premiums for the full term and, if no claim is made, the policy is designed to return them.
Mortgage Protection
Sized to your remaining balance and the years left on it, so the house is paid off outright. Also available with the CBO100 cash-back option.
CBO100 availability, terms and cost vary by carrier and product, and it is not offered on every policy. We'll confirm what's available for your situation.
02 — PERMANENT / WHOLE LIFE
Coverage that never expires — and money that builds while it waits
Whole life lasts your entire life, the premium never increases, and part of every payment builds guaranteed cash value you can borrow against. That cash value is what makes whole life a financial tool as well as a death benefit, and it's the engine behind several strategies we build for clients.
Prompt: Generate Image for this exact pain point SOLUTION, realistic
Infinite Banking is a strategy that uses a whole life policy, not a product in itself. Policy loans reduce the death benefit and cash value if not repaid, and accrue interest. Dividends are not guaranteed.
Prompt: Generate Image for this exact pain point SOLUTION, realistic
03 — FINAL EXPENSE
Whole life built for one job: the funeral your kids shouldn't pay for
Final expense is whole life in a smaller, simpler package designed for people aged roughly 50 to 85. Coverage is modest — usually $5,000 to $50,000 — the premium never increases, the benefit never decreases, and the claim is designed to pay quickly, because the funeral home wants payment the same week.
Guaranteed issue policies typically pay only return of premium plus interest if death occurs within the first two to three years, other than by accident. We'll always test you for immediate full benefit coverage first.
04 — INDEXED UNIVERSAL LIFE
#4Index-linked growth with a floor, wrapped in a death benefit
An IUL credits interest based on the performance of a market index, with a 0% floor — so a year the index falls doesn't take your cash value down with it. That downside protection, combined with a death benefit and different tax treatment on distributions, is what separates it from simply buying an index fund. It works best when started young, because the internal cost of insurance rises every year as you age.
Prompt: Generate Image for this exact pain point SOLUTION, realistic
Premiums are flexible, not fixed, and the cost of insurance increases with age. An underfunded IUL can lapse. Illustrations are not guarantees — actual results depend on policy design, index performance, caps and internal costs.
Prompt: Generate Image for this exact pain point SOLUTION, realistic
05 — ANNUITIES
Turn what you've saved into a second income you can't outlive
An annuity is a contract with an insurance carrier: you place a lump sum with them, it grows tax-deferred, and at retirement it converts into predictable income. You can fund one with new money or roll over an existing 401(k) or IRA without triggering a taxable event. For a lot of people it becomes the paycheck that arrives whether the market cooperates or not.
Guarantees are backed by the claims-paying ability of the issuing carrier. Annuities commonly carry surrender charges for early withdrawal, and withdrawals before age 59½ may incur a tax penalty. Not FDIC insured.
06 — HEALTH INSURANCE
Cover the bills that arrive while you're still here
Life insurance handles what happens if you're gone. Health insurance handles the doctor's visits, prescriptions and hospital bills that happen while you're very much alive — and for most families it's the larger monthly line item. We help you compare marketplace and private options, and fill the gaps the main plan leaves behind.
Prompt: Generate Image for this exact pain point SOLUTION, realistic
Plan availability, networks and pricing vary by county and by year. Medicare guidance is available separately — ask us.
WHY FAMILIES CHOOSE THIS AGENCY
Licensed. A-Rated Carriers. One Agent Who Actually Picks Up.
We thought we could only afford a small policy. We left with double the coverage for less than we were paying.
I had no idea how to compare companies. He only brought me A-rated carriers with 100-year track records.
My whole life policy builds cash value and earns a dividend. Protection we need, and money I can reach.
The annuity pays us every month in retirement, for as long as we live. A paycheck we thought had ended.
My IUL follows the index when it climbs and didn't lose ground the year the market fell.
I asked what happens if I'm gone. He showed me years of my income replaced, not a few weeks.
With the rider, if I never file a claim I get back every dollar I paid in. It still sounds unreal.
Our policy covers the whole 30-year mortgage plus a year of income. Nobody is packing up this house.
The refund is set to land about five years before I retire and five before the mortgage is paid off.
3 EASY STEPS
My Simple Path to Protecting My Family
1
STEP 01
Book Your Free Call
Schedule a quick 20-minute call with a licensed agent — no pressure, no obligation.
2
STEP 02
Get Your Custom Plan
We compare top-rated carriers and build a coverage plan that fits your budget and goals.
3
STEP 03
Get Covered & Protected
Sign your policy and rest easy knowing your family is protected — for life.
Meet the Team of Professionals
Behind every Nooga Strong client is a veteran-led team with decades of combined experience protecting families. From our parent agency's Hall of Fame producers to boots-on-the-ground support here in Chattanooga, every member of this team is personally invested in your family's financial security. Tap any photo to book directly with that team member.
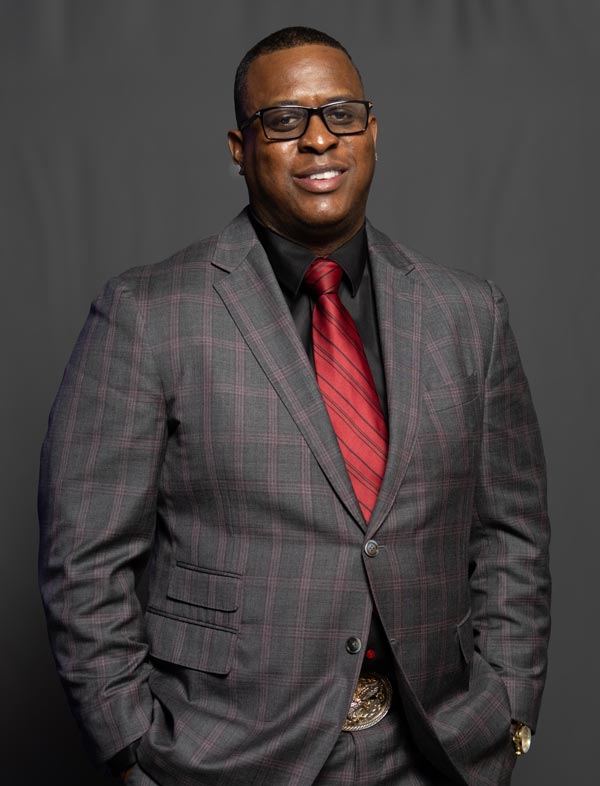
Kendall B. Clark, Sr.
CEO & Agency Owner, Invincible Insurance


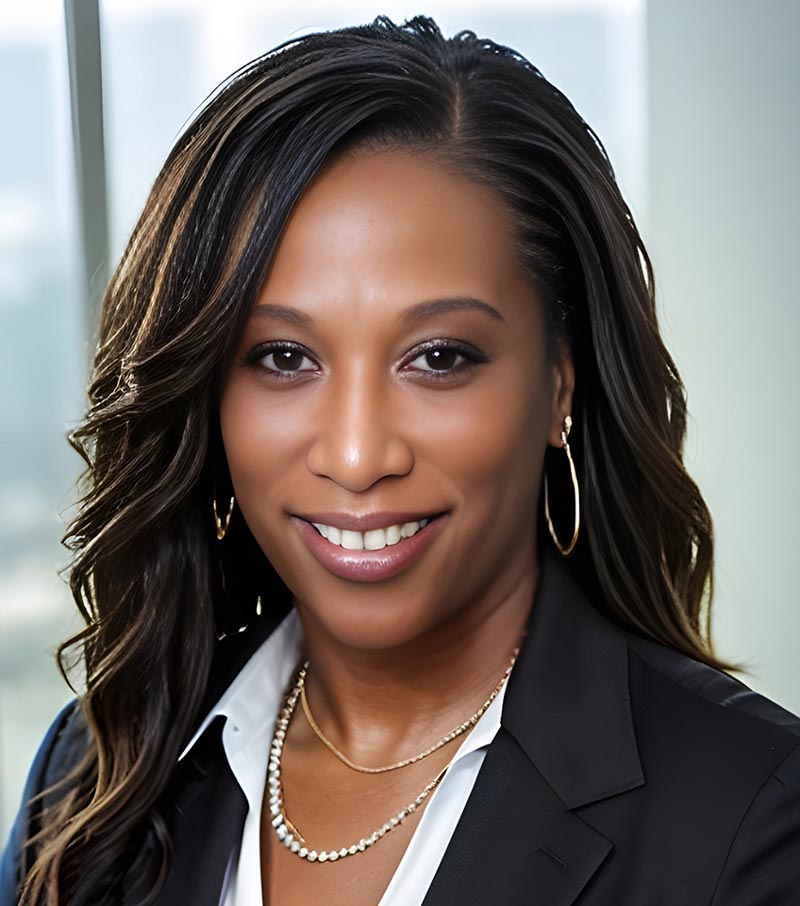
Crystal Clark
Agency Owner, Clarity Financial LLC
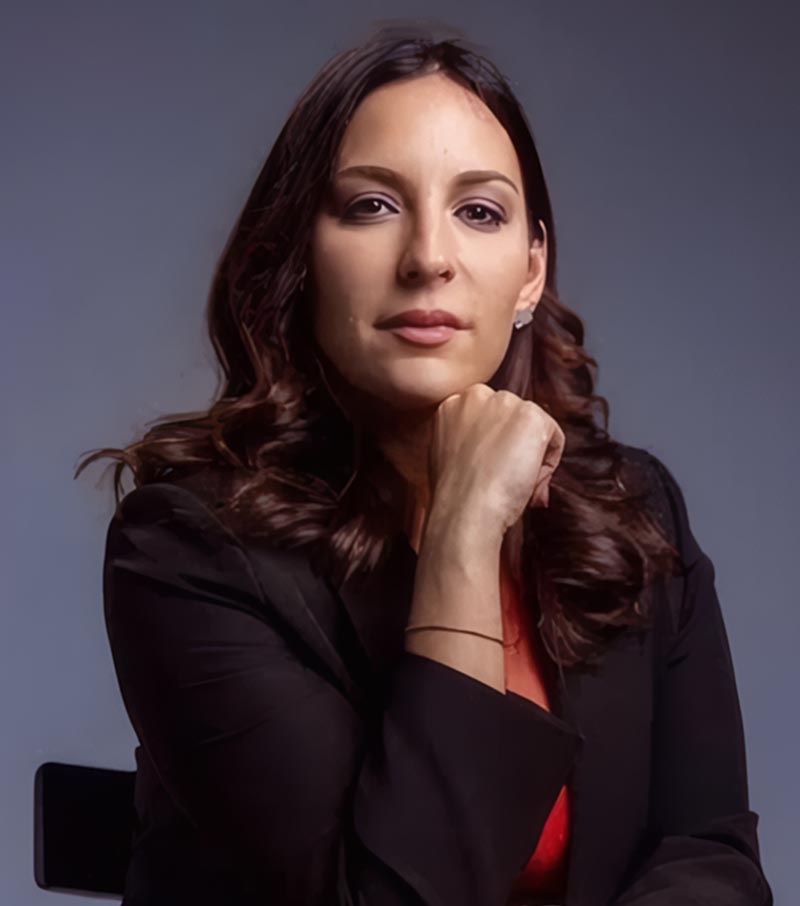
Leslie Scofield
Agency Founder, Ashes to Assets
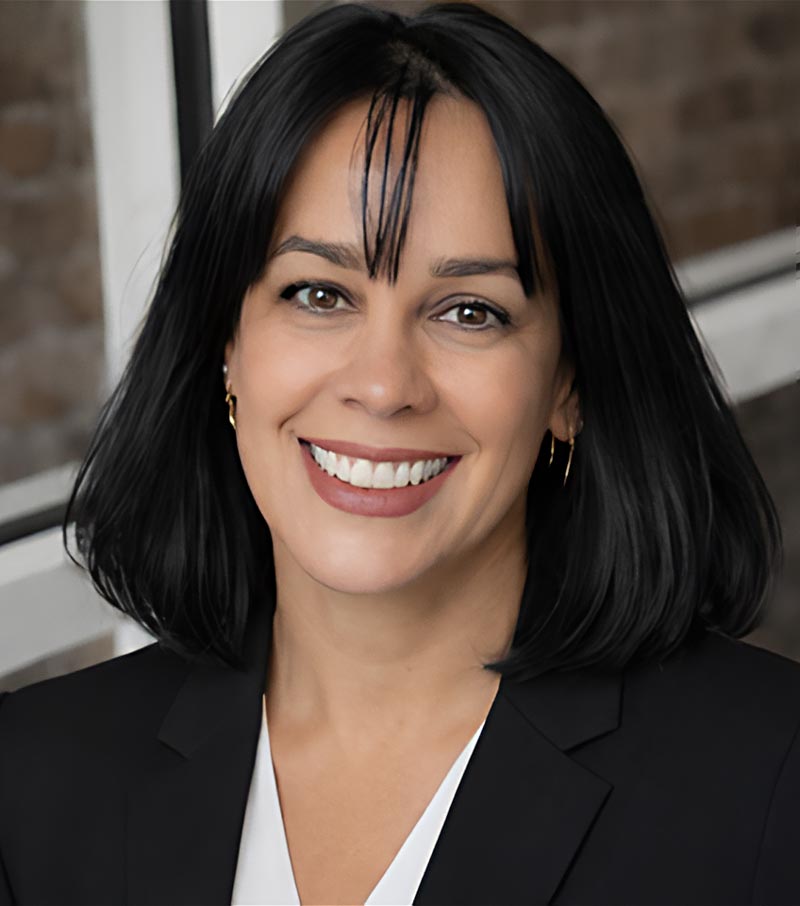
Susan Randall
Insurance Consultant
Travis Pace
Founder, Nooga Strong FFL
STILL NOT SURE?
Frequently Asked Questions
PROMPT: RESEARCH ONLINE FIRST THEN GENERATE ME A PROMPT FOR THE TOP 10 MOST ASKED QUESTIONS FOR MY LIFE INSURANCE POLOICY TYPE.
Question 1: How do you lorem ipsum?
Lorem ipsum dolor sit amet, consectetur adipisicing elit. Autem dolore, alias, numquam enim ab voluptate id quam harum ducimus cupiditate similique quisquam et deserunt, recusandae.
Question 2: What do you lorem ipsum?
Lorem ipsum dolor sit amet, consectetur adipisicing elit. Autem dolore, alias, numquam enim ab voluptate id quam harum ducimus cupiditate similique quisquam et deserunt, recusandae.
Question 3: When can I lorem ipsum when I buy?
Lorem ipsum dolor sit amet, consectetur adipisicing elit. Autem dolore, alias, numquam enim ab voluptate id quam harum ducimus cupiditate similique quisquam et deserunt, recusandae.
Question 4: What if I feel stuck with lorem ipsum?
Lorem ipsum dolor sit amet, consectetur adipisicing elit. Autem dolore, alias, numquam enim ab voluptate id quam harum ducimus cupiditate similique quisquam et deserunt, recusandae.
Title or Question
Describe the item or answer the question so that site visitors who are interested get more information. You can emphasize this text with bullets, italics or bold, and add links.
Title or Question
Describe the item or answer the question so that site visitors who are interested get more information. You can emphasize this text with bullets, italics or bold, and add links.
Title or Question
Describe the item or answer the question so that site visitors who are interested get more information. You can emphasize this text with bullets, italics or bold, and add links.
Title or Question
Describe the item or answer the question so that site visitors who are interested get more information. You can emphasize this text with bullets, italics or bold, and add links.
Title or Question
Describe the item or answer the question so that site visitors who are interested get more information. You can emphasize this text with bullets, italics or bold, and add links.
Title or Question
Describe the item or answer the question so that site visitors who are interested get more information. You can emphasize this text with bullets, italics or bold, and add links.
SOCIAL PROOF #1 (SAME EXACT SOCIAL PROOF FROM THE HERO SECTION
PROMPT: GENERATE A FINAL RECAP OF THE ENTIRE WEBSITE, SENSE OF URGENCY, WHY THEY MUST TAKE ACTION TODAY
PROMPT: GENERATE THE FINAL REASON THEY MUST CALL YOU TODAY TO SOLVE THE LIFE INSURANCE PROBLEM. (PAIN & PROBLEMS THAT WILLL CONTIUNE OF YOU DONT TAKE ACTIONS NOW...THEN GIVE ME THE BEST 3 BULLET POINTS FOR: BENEFITS, INSTANT SUCCESS, AND BONUS FOR TAKING ACTION TODAY.
Benefits you get when joining
Second thing you get instant access to
Third thing you get as a bonus today (I ALWAYS GIVE AWAY A $25.00 GIFT CARD FOR BOOKING AND SHOWING UP TOM Y APOPINTMENT FROM HERE ITS CHEAPER THAN BUYING LEADS
PROMPT: GENERATE EXPRESS URGENCY HEADLINE ABOVE MY FINAL VSL VIDEO
YOUR NAME, AGENT/ AGNECY OF COMPANY NAME
NOOGA STRONG - FFL
SERVICES
LOCATIONS
CUSTOMER CARE

Nooga Strong - FFL is an insurance brokerage located in Chattanooga, Tennessee, affiliated with Family First Life.
Coverage, pricing, and availability can change by company, state, age, and health. Any examples on this site are for illustration only and are not a guarantee. Any guarantees are backed by the issuing company.
By submitting your info you agree we may contact you by phone, text, and email at the number and address you provide, including through automated technology. Consent is not required to buy. Message and data rates may apply. Reply STOP to opt out.
© 2026 Nooga Strong - FFL. All rights reserved.